SEPTEMBER 2026 NEWSLETTER
Even Ohio Stadium Isn't Big Enough: Equivalent of an OSU Game Day Crowd Loses SNAP
By Joshua Goodwin
107,573 people is a lot of people. I’ve spent a lot of time during the last month trying to visualize that number. I thought about it as being roughly three times the population of Lancaster, Ohio, as I knew it when I graduated high school. That didn’t help. I tried thinking about it as close to everyone that lives in Vinton, Monroe, Morgan, Harrison, Noble, Paulding, and Meigs counties. I still had trouble grasping it.
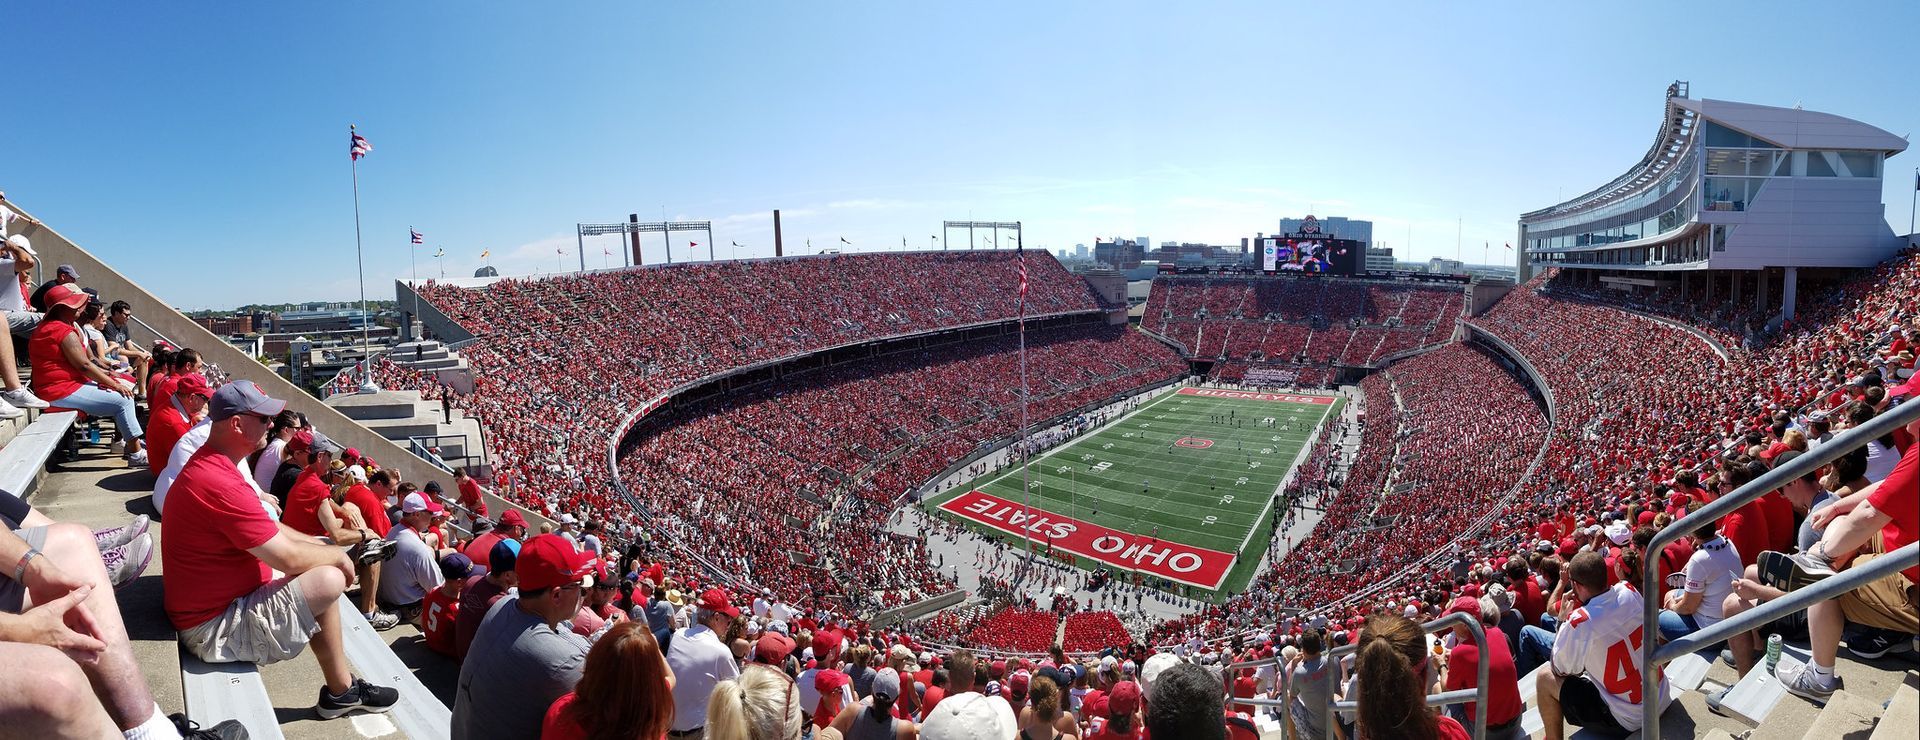
Then it hit me: 107,573 is a little bit more than how many people will fit into the Horseshoe when the Buckeyes take the field for a Saturday home game this fall. An OSU home game is one of the few times and places where you can see 100,000 people at once. It’s an amazing perspective to sit in Ohio Stadium and be surrounded by that many people.
So why have I been so fixated on understanding what that many people look like? 107,573 is how many Ohioans lost their food stamps between the passage of HR1 in July 2025 and May 2026. As a reminder, HR1 requires states to pay more of the costs of SNAP and imposes even harsher work requirements, and it has contributed to a massive decrease in the number of people getting SNAP across the country.
ALSO IN THIS ISSUE:
Drop in State Share of Education Funding Leaves Taxpayers to Pick Up the Tab | Proposed Rule Would Weaken Bank Obligations Under Community Reinvestment Act | Affordable Care Act Enrollment Falls in Ohio
Here in Ohio, 107,573 people lost the help they need to keep food on their tables. They now face ever-rising grocery prices with less help than they had a year ago.
In less than a year, more than a Horseshoe full of people lost SNAP benefits. More than 50,000 of them were kids.
It gets worse when you look at specific counties. For example, in Franklin County alone, the number of kids on SNAP dropped by more than 20% in less than a year. That’s more than 16,000 kids who may be starting school this year hungrier than they were when they started last school year.
And there’s every reason to believe these numbers are only going to grow.
Many of those families now have to answer the question, “Should I pay for food to eat, rent to stay housed, or for those medications the doctor says I really need?” This question may lead some people to lose their housing. Some may see their health deteriorate. Kids will have a harder time learning. HR1’s impact on the SNAP program is making life harder for a lot of Ohioans.
As you're cheering on the Scarlet and Gray this fall, take a moment to look at the crowd. Every seat in Ohio Stadium will be filled. Then remember that even that crowd isn't large enough to hold everyone who has lost SNAP assistance in Ohio since HR1 became law.
Drop in State Share of Education Funding Leaves Taxpayers to Pick Up the Tab
By Tim Johnson
Ohioans are dealing with increased prices on everything from groceries to fuel, and many are grappling with rising property taxes that are making it more difficult to afford their homes. As we get closer to Election Day, many Ohioans may be reluctant to support school levies that could raise their property taxes even if they recognize their local district is facing financial instability. The Ohio General Assembly's failure to invest in public schools has shifted the burden to taxpayers, who are also experiencing economic uncertainty.
In Fiscal Year (FY) 2019, the state of Ohio contributed 46% of all school funding, with local communities paying the remaining 54%. That share has dropped drastically over the last several years. In FY 2027, the state is expected to contribute just 32% of school funding, leaving local communities to pick up the rest of the tab. Nationally, Ohio ranks well below average, coming in 41st in state education funding. The drop in the state's share of funding has real consequences—not just for our local school districts but for all Ohioans.
School districts find themselves in the difficult predicament of going to the ballot with a levy that voters may reject or cutting programs and personnel in an attempt to save money. If the state does not increase its share of funding, school districts will continue to face difficult choices, and taxpayers will be asked to reach into their pockets to pay for the legislature’s funding gap.
OPLC and our legal aid partners across Ohio see firsthand what happens when schools do not have adequate funding: low-income students attend schools with larger classroom sizes and fewer administrators than their peers in wealthier districts. There is less funding to help English language-learning students, and families with children who have individualized education programs (IEPs) must constantly battle for the resources they need to make their education accessible. Without adequate funding from the state, low-income students are left with less support and more barriers to success. The next state operating budget cycle begins in 2027, and OPLC will continue to work with lawmakers and partner organizations to ensure that all students are able to attend a school that is adequately and fairly funded.
Proposed Rule Would Weaken Bank Obligations Under Community Reinvestment Act
By Zack Eckles
A major proposal from federal banking regulators could significantly reshape how banks invest in underserved communities across the country.
The Office of the Comptroller of the Currency (OCC) and Federal Deposit Insurance Corporation (FDIC) have jointly proposed sweeping changes to the Community Reinvestment Act (CRA), a landmark law enacted in 1977 to combat predatory lending practices such as redlining. The CRA encourages banks to better meet the needs of borrowers in low and moderate-income neighborhoods.
The Federal Reserve System, FDIC, and OCC oversee CRA compliance. These agencies evaluate banks and assign them a CRA Compliance Rating, which is considered by regulatory agencies when the bank applies for licenses or regulatory approval for merger, acquisition, or branching.
Community advocates like the
National Community Reinvestment Coalition (NCRC) warn the proposed rule would risk the closure of thousands of branches in underserved communities, lower incentives for affordable housing and community development investment and financing, and threaten CRA credit for banks that make grants and donations to nonprofits.
Another significant change would be raising the asset threshold that determines how banks are evaluated under the CRA. Under current rules, banks with more than $1.649 billion in assets are classified as large banks and face more extensive reporting requirements. The proposal would raise that threshold to $10 billion. NCRC estimates that 417 banks would no longer be required to report critical information about their investments, community services, and small business lending activities.
Under this rule, NCRC estimates that the number of “large banks” for CRA purposes in Ohio would be cut by 43%. It would also end some of the protections that help keep 176 bank branches open in low- and moderate-income communities in Ohio. These changes have the potential to make it harder for low-income Ohioans to access the banking services they need.
FDIC’s press release announcing the proposal as well as a link to the proposed rule can be found
here. Public comments on the proposal must be received by Oct. 13, 2026.
Affordable Care Act Enrollment Falls in Ohio
By Danielle DeLeon Spires
Ohio experienced one of the sharpest declines in ACA Marketplace enrollment in the nation from 2025 to 2026, according to
a leading health policy resource organization. KFF found that 49 out of 50 states saw a drop in ACA Marketplace enrollment.
Ohio’s enrollment dropped 32% from 497,443 in 2025 to 336,058 in 2026. This decrease in enrollment follows the Dec. 31 expiration of enhanced premium tax credit subsidies, which were available to everyone, regardless of income. Without that financial assistance, many consumers faced substantial premium increases and were forced to reconsider their coverage options.
Health care premium prices are anticipated to continue to
rise for marketplace plans in 2027, as states implement administrative changes for Medicaid enrollment. An analysis by the Center for American Progress found that the 11 insurers remaining in Ohio’s marketplace are proposing to increase premiums on average by 14.7%. This percentage increase is lower than 2026, however, it still far outpaces most cost-of-living adjustments and inflation.